A comparative market analysis (CMA) estimates what a property is worth by comparing it to similar homes that recently sold nearby. You line up the subject property against three to five comps, adjust each comp's sale price for differences like size, condition and garage space, and use the adjusted prices to set a value range.
Agents use CMAs to price listings, buyers use them to set offers, and investors use the same method to estimate ARV. Below is a CMA template you can copy, a worked adjustment example with the math shown, and the three ways to get a CMA done.
What is a comparative market analysis?
Think of a CMA as a property's data-driven resume. It shows what buyers have actually paid for homes like this one, in this neighborhood, recently. It is the same idea as checking what cars with the same make, model and mileage sold for before you buy one.
A CMA is not just a price tag. It explains why a home is worth what it is, with evidence you can point to in a negotiation. That is what keeps you from overpaying, or from listing too low.
A CMA is also not an appraisal. Agents and investors prepare CMAs to price and negotiate. A lender's appraisal is a formal valuation by a licensed appraiser. Both use comps, but the appraisal is the official one for financing.
The core parts of a CMA template
Every solid CMA is built on three pieces:
- The subject property: the home you are valuing, with its square footage, bed and bath count, lot size, age, condition and any standout features. Everything else is compared to this.
- Comparable properties ("comps"):3 to 5 similar homes nearby that sold recently. The best comps match the subject in size, layout, age, condition and location.
- Adjustments: no two houses are identical, so you add or subtract value from each comp's sale price to account for differences. This is what makes the comparison apples-to-apples.
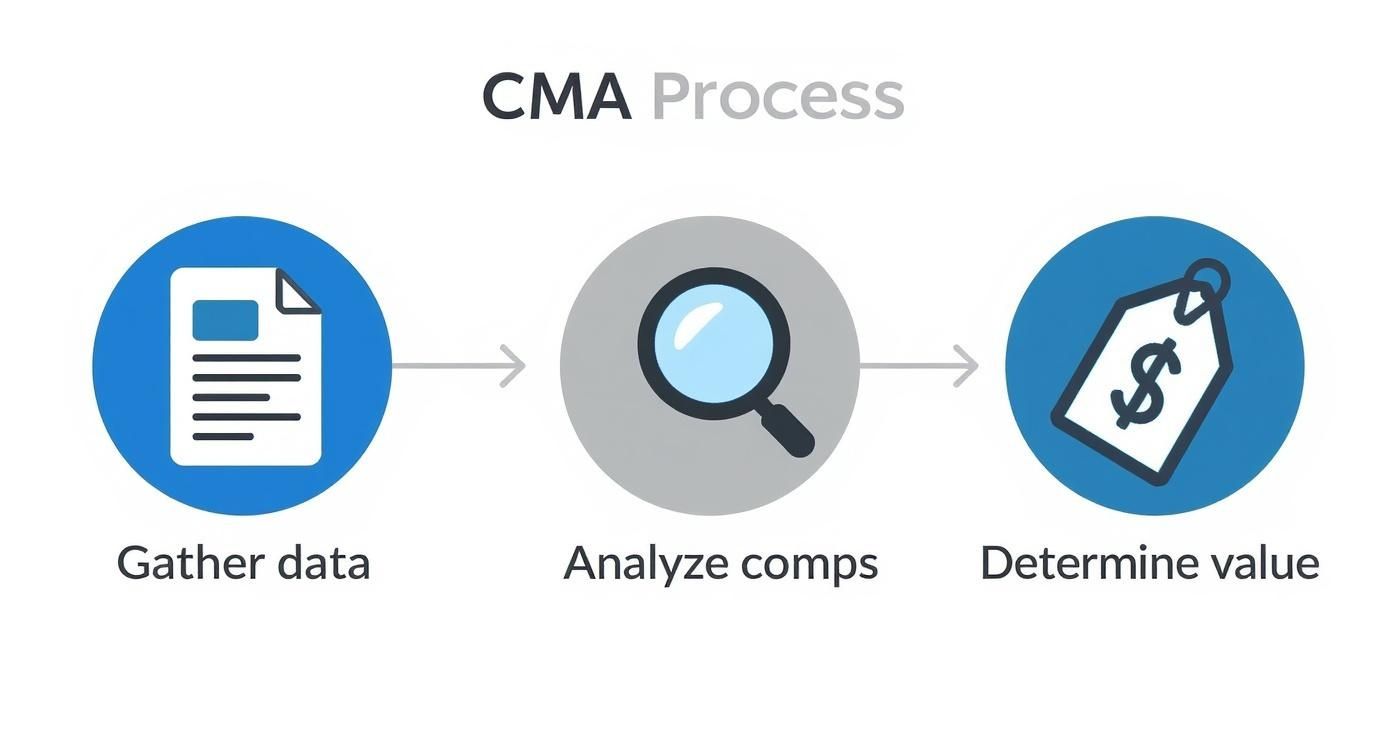
The infographic below shows the basic flow: gather the data, compare against comps, then pin down an estimated market value.
A complete CMA report usually includes these sections:
| Component | What it tells you | Why it matters |
|---|---|---|
| Subject property details | Sq. ft., beds/baths, lot size, age, condition | Sets the baseline for a fair comparison |
| Comparable properties | 3 to 5 similar, recently sold homes nearby | Real-world evidence of market value |
| Sales data | Sale price, sale date, days on market for each comp | Shows what buyers are actually paying now |
| Adjustments | Value added or subtracted for differences (garage, pool, kitchen) | Keeps the comparison accurate and fair |
| Photos and map | Visuals of the subject and every comp | Lets you check similarities and differences yourself |
| Value range | The final, data-backed price range | Gives you a defensible number for a list price or offer |
Comparative market analysis template (copy this)
Use this grid for any property. Put the subject in the first column and one comp in each column after it. Fill in the sale data, then enter an adjustment for every feature where a comp differs from the subject.
| Field | Subject | Comp 1 | Comp 2 | Comp 3 |
|---|---|---|---|---|
| Address | ||||
| Sale price | (to be estimated) | |||
| Sale date | n/a | |||
| Distance from subject | n/a | |||
| Days on market | n/a | |||
| Living area (sq. ft.) | ||||
| Beds / baths | ||||
| Lot size | ||||
| Year built | ||||
| Condition / updates | ||||
| Garage / parking | ||||
| Pool, basement, other | ||||
| Sale type | n/a | (standard, foreclosure, short sale) | ||
| Total adjustments (+/-) | n/a | |||
| Adjusted sale price | n/a |
The one rule to remember: you adjust the comp, never the subject. If a comp is better than the subject in some way, subtract value from the comp. If it is worse, add value. The question each adjustment answers is "what would this comp have sold for if it were just like the subject?"
Worked example: adjusting three comps
Here is the template filled in for a hypothetical subject property. The dollar adjustments are illustrative. In a real CMA you set them from local sales, for example by comparing homes that sold with and without a garage in the same area.
Subject: 1,650 sq. ft., 3 beds, 2 baths, two-car garage, updated kitchen. For this example we value extra living area at $90 per sq. ft., an updated kitchen at $15,000, a half bath at $6,000 and a second garage bay at $8,000.
| Field | Comp 1 | Comp 2 | Comp 3 |
|---|---|---|---|
| Sale price | $342,000 | $371,000 | $355,000 |
| Living area | 1,550 sq. ft. | 1,700 sq. ft. | 1,650 sq. ft. |
| Size adjustment | +100 x $90 = +$9,000 | -50 x $90 = -$4,500 | $0 |
| Baths | 2 ($0) | 2.5 (-$6,000) | 2 ($0) |
| Kitchen | Original (+$15,000) | Updated ($0) | Updated ($0) |
| Garage | Two-car ($0) | Two-car ($0) | One-car (+$8,000) |
| Net adjustment | +$24,000 | -$10,500 | +$8,000 |
| Adjusted price | $366,000 | $360,500 | $363,000 |
Check the math. Comp 1: $342,000 + $9,000 + $15,000 = $366,000. Comp 2: $371,000 - $4,500 - $6,000 = $360,500. Comp 3: $355,000 + $8,000 = $363,000.
The three adjusted prices sit in a tight range, $360,500 to $366,000. The simple average is $1,089,500 / 3 = about $363,200. Comp 3 needed the smallest adjustment, so it deserves the most weight, and it lands right at $363,000. A reasonable value for the subject is about $363,000, with $360,500 to $366,000 as the range.
Notice what the raw sale prices would have told you. They run from $342,000 to $371,000, a $29,000 spread. Adjustments shrink that to $5,500. That is why price per square foot on its own can mislead; our post on why price per square foot lies about ARV goes deeper on the adjustment grid.
How to read a CMA report
A CMA can look like a wall of numbers and jargon. Start with the subject property section, which sets the baseline, then spend most of your time on the comps. They are the evidence behind the final number.
What makes a good comp
- Proximity: the closer, the better, ideally in the same neighborhood or subdivision. A home across a major road or in a different school zone can be in a different micro-market.
- Recency: comps that sold in the last three to six months show current buyer behavior. Older sales need a time adjustment if prices have moved.
- Similar features: the best comps match the subject in size, bed and bath count, age and condition, so they need few adjustments.
- A normal sale: foreclosures, short sales and sales between family members often close below market. Leave them out or adjust for them, or they will drag the value down.
Buyer's tip: look at the sale dates. If every comp sold months ago for less than today's asking price, either the market is rising or the seller is being optimistic. Newer comps will tell you which.
What to check in the adjustments
Common adjustments cover upgrades (a renovated bath or finished basement), condition (a roof at the end of its life), and amenities (a pool, an extra garage bay, a corner lot). Make sure each one runs in the right direction: a comp with a feature the subject lacks gets a downward adjustment.
Also look at how large the adjustments are. A comp that needs big adjustments on several features is a weak comp. If you cannot find good matches, our guide on estimating value with only one or two good sales covers how to work with thin data.
The market data behind the numbers
https://www.youtube.com/embed/vhOCI2eXP8E
A CMA is also a snapshot of the local market. Market conditions explain why comps sold where they did and tell you how to use the number. These are the metrics to watch:
- Days on market (DOM): how long homes sit before going under contract. Short DOM means a hot market where you need to move fast. Long DOM means more room to negotiate.
- List-to-sale price ratio: sale price divided by list price. Above 100% means homes are selling over asking, often with multiple offers. Below 100% means sellers are accepting less.
- Months of inventory: how long it would take to sell every active listing at the current pace. A common rule of thumb is that under about four months favors sellers and over about six favors buyers.
Put those together and you know how to read the comps. In a tight seller's market, comps that sold above list are not errors; they reflect competition. In a buyer's market, comps that sat 60 days and sold below asking give you evidence to negotiate harder. For other ways to value a property alongside comps, see our overview of real estate property valuation methods.
How to get a comparative market analysis
You have three options, and they are not mutually exclusive.
1. Ask a real estate agent
A local agent can pull comps from the MLS, walk the property and adjust for condition in a way that public data cannot. Agents often prepare CMAs at no charge when they hope to earn your listing or represent you as a buyer. Ask to see the comps and adjustments, not just the final number.
2. Use an online comparative market analysis tool
Online tools range from automated valuation models (AVMs), like the estimates on Zillow and Redfin, to investor tools that show the comps and adjustments behind the number. AVMs are a quick starting point, but they cannot see a new kitchen or a failing roof.
For investors, the useful tools show their work. FlipSmrt, for example, pulls recent MLS sold comps near the property, adjusts them for differences and returns ARV along with rehab costs and MAO in under 5 minutes. For a list of no-cost options, see our roundup of ways to get a comparative market analysis free.
3. Build your own with the template
Pull recent sales from public records, listing sites or an agent, then fill in the template above. Doing your own CMA takes longer, but you learn the neighborhood and you know exactly which comps went into the number. It is a good habit for anyone making offers regularly.
How technology is changing CMAs
The stack of printed pages is giving way to digital reports. Modern CMA tools pull sales data automatically and present it visually, with maps of comps around the subject and charts that show whether neighborhood prices are rising, falling or flat.
That speeds up the data gathering, but it does not replace judgment. Software cannot always tell that a comp sold low because of a divorce, or that the "updated kitchen" in a listing was a rough DIY job. Someone still has to check that each comp is truly comparable and flag the outliers.
Key takeaway: technology gives you the "what" (the raw data). A person who knows the area supplies the "why" (the story behind each sale). The best CMA uses both.
If you are comparing platforms, our breakdown of real estate investment analysis tools covers the main options.
Using a CMA to make an offer
With a finished CMA, you can anchor your offer in evidence instead of a feeling. If recent comps sold right around the asking price, the seller has priced it fairly and an offer near list is a strong opening.
If the CMA shows the home is overpriced, say by $15,000, use the comps to justify a lower number. "Based on the recent sales on Maple Street and Oak Avenue, we believe $X reflects the market" carries more weight than "we think it's worth less."
| If the CMA shows... | It likely means... | Your offer strategy |
|---|---|---|
| The home is priced in line with strong comps | The seller knows the property's value | Offer at or near asking. A lowball will probably be dismissed. |
| The home is priced well above the adjusted comps | The seller is testing the market or is attached to a number | Offer lower and cite the specific comps that support it. |
| The home is priced slightly low and comps sell fast | The seller may be trying to start a bidding war | Use your CMA value as a ceiling so you do not overpay in the moment. |
Price is only part of the offer. If comps go under contract in days, a shorter inspection period can help you stand out. Before you commit, work through our real estate due diligence checklist for inspections, title and the rest.
If you are an investor, the CMA value is your ARV starting point when the home is already renovated, or the "as-is" value when it is not. For a flip, estimate ARV from renovated comps instead, then work back to your offer.
Frequently asked questions
What is a comparative market analysis?
A comparative market analysis is an estimate of a property's market value based on similar homes that recently sold nearby. Each comp's sale price is adjusted for differences from the subject property, and the adjusted prices set a value range. Agents use it to price homes, and buyers and investors use it to set offers.
How do I get a comparative market analysis?
Ask a local real estate agent, use an online comparative market analysis tool, or build your own with recent sales and a template like the one above. Agents often provide one at no charge. Whichever route you take, ask to see the comps and adjustments behind the number.
What is the best comparative market analysis tool?
The best tool is the one that shows its comps and adjustments, not just a single estimate. Automated estimates on listing sites are a quick starting point. Investor tools that use recent MLS sold comps and adjust them are more useful for making an offer.
How is a CMA different from an appraisal?
A CMA is prepared by an agent or investor to price or negotiate. An appraisal is a formal valuation by a state-licensed appraiser, usually ordered by a lender to confirm the home supports the loan. Both rely on comps, but the appraisal follows stricter standards.
Can I trust an online home value estimate?
Use it as a starting point, not as your offer. Automated estimates cannot see condition, such as a renovated kitchen or a leaking roof. A CMA built from comps you have checked, adjusted for the actual condition, is a better basis for a decision.
What if there are no good comps for a property?
This happens with unusual homes and in rural areas. Widen the search area or time window, make larger adjustments, and look at active and pending listings to gauge competition. Treat the result as a wider range and give more weight to the closest matches.
Run a CMA on a real deal. FlipSmrt pulls recent sold comps, adjusts them for differences, prices the rehab line by line and gives you ARV, MAO and a go/no-go verdict in under 5 minutes. Analyze a property free (your first 3 analyses are free).